Renewal season, 2026

Policy reviews are booking through late autumn — request a review

Coda Vale.

An independent insurance brokerage for households, landlords and small trades.

The policy review, in plain language

Cover you can actually read, placed by a broker who stays on the file.

Coda Vale compares cover across several carriers, writes the recommendation on a single page, and comes back to it before every renewal — so the wording keeps matching the way you really live and work.

A set of house keys being handed across a table beside paperwork
Most reviews start the week something changes — a move, a new driver on the policy, a first tenant, or a trade taking on its first contract.

Index — what we place

Six lines, and who each one suits

Each entry describes what the policy is actually for. If your situation sits between two of them, that is usually a sign the review is worth doing.

01

Home & contents

Structure, contents and personal liability for an owner-occupied home, with the dwelling figure set against rebuild cost rather than what the property would sell for.

Suits owners who have renovated, added a workshop or a garden studio, or never revisited the figure after moving in.

02

Auto & multi-vehicle

Liability, collision and comprehensive across one or several vehicles, including household members who have just started driving and cars kept off the road part of the year.

Suits households adding a driver, running a second car seasonally, or carrying two separate policies that could sit together.

03

Renters

Contents, personal liability and temporary accommodation cover for tenants. Inexpensive, routinely skipped, and the line that most often surprises people after a neighbour’s leak.

Suits tenants, house-sharers and anyone storing a bicycle, instrument or laptop worth more than the standard sub-limit.

04

Landlord & second property

Buildings cover, landlord liability and loss of rent for a let property, plus the different wording a place needs when it stands empty for part of the year.

Suits first-time landlords, inherited property, and holiday lets that a standard home policy quietly excludes.

05

Small trade & artisan

General liability, tools and equipment, and the certificate wording a main contractor or venue will ask to see before you are allowed on site.

Suits joiners, electricians, gardeners, decorators and makers taking on their first contract work.

06

Umbrella & excess liability

A layer of liability that sits above the limits on your home and auto policies and responds once those are exhausted.

Suits anyone with savings to protect, a pool or trampoline, a teenage driver, or a role that makes them visible.

How a review works

Four steps, no obligation at any of them

A review takes about a week end to end, and most of that week is us waiting on carriers rather than you filling anything in.

Step one

Send what you have

The declarations page of each current policy is enough to start. If you cannot find it, tell us the carrier and renewal month instead.

Step two

We read it properly

We mark the limits, deductibles, exclusions and endorsements, and flag anything that no longer matches what you told us about the household.

Step three

One page back

You get a single page: what you hold now, what we would change, what each option costs, and what we would leave exactly as it is.

Step four

Placement and renewal watch

If you move, we handle the paperwork and cancellation timing. Either way we diary the renewal date and come back before it lands.

Reading your policy

Four decisions worth understanding first

These are the four points where most policies drift away from the household they were written for. You can check all of them yourself in about ten minutes.

A furnished living room with sofa, rug and bookshelves in daylight
Rebuild cost is about materials, labour and access — not the market value of the room you are standing in.

Deductible against premium

Raising the deductible lowers the premium, but only helps if you could pay that amount tomorrow without borrowing. Set it at a number you could absorb twice in one year, since storms rarely arrive alone.

Ask us: what the next deductible band would actually save you.

Replacement cost against actual cash value

Replacement cost pays to buy the item again today. Actual cash value pays what the old item was worth after depreciation. The difference is invisible on the premium line and very visible at claim time, particularly on roofs and contents.

Ask us: which basis your contents and roof are currently written on.

Liability limits and the umbrella test

Add up what you would lose if a judgment ran past your home and auto liability limits. If that figure is larger than the limits themselves, an umbrella layer is usually the cheapest cover on the whole file.

Ask us: where your current limits stop.

Endorsements worth asking about

Water backup, ordinance and law, scheduled items for jewellery or instruments, and home-business use of a room are all added by endorsement. Standard wordings limit or exclude each of them by default.

Ask us: which of these you already hold, and which you do not.

The practice

Independent, and plain about how that works

Coda Vale is run by Rowan Alder, a broker who left a single-carrier desk to stop recommending the only product on the shelf. The practice is deliberately small: every file is read by the person who placed it.

  • We are not tied to one carrierWe hold appointments with several, so a recommendation can be compared against alternatives rather than defended.
  • We are paid commission by the carrierIt is built into the premium, it does not change what you pay us directly, and we will tell you when one option pays us more than another.
  • We do not cold callReviews happen when you ask for one or when your renewal is approaching and we have something worth saying.
  • We stay on the file at claim timeYou deal with the carrier’s adjuster, but we read the wording alongside you and chase what has gone quiet.
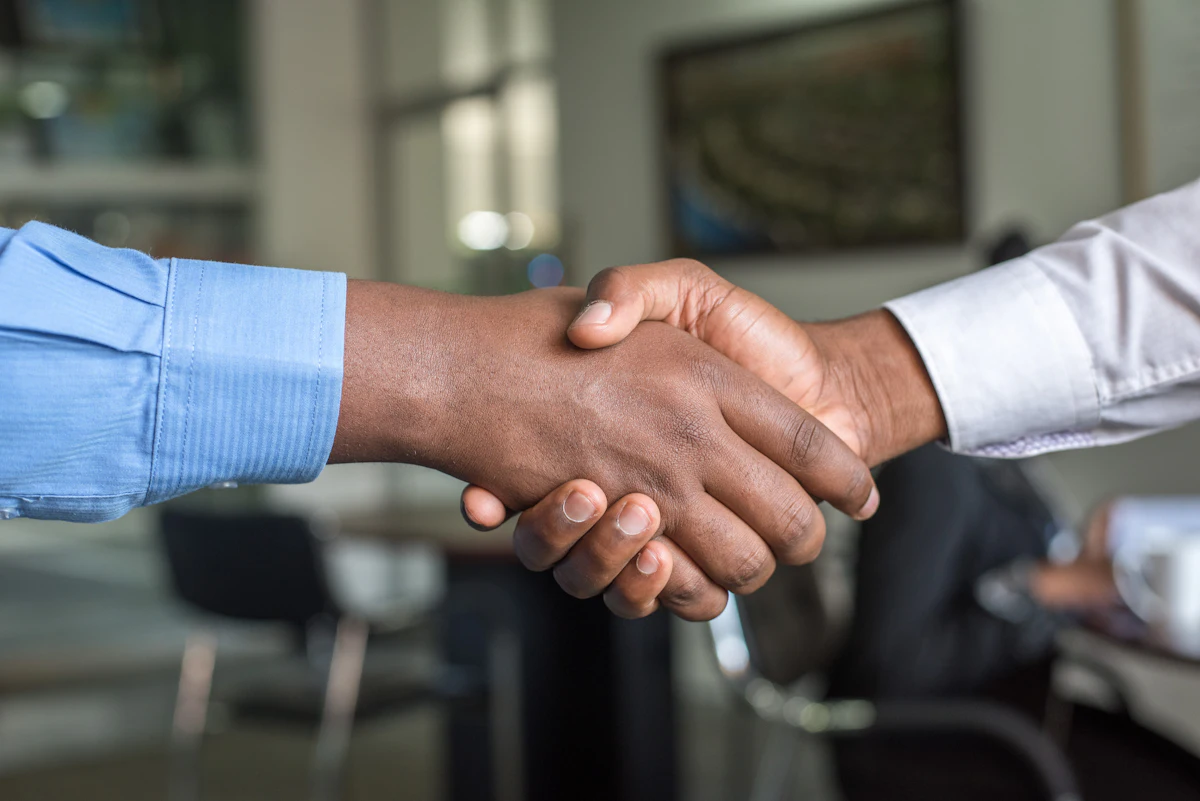
Two people shaking hands across a desk at the end of a meeting
Reviews are done by email or over a call — whichever gets the declarations page in front of us soonest.

Common answers

Questions we are asked most weeks

If yours is not here, put it in the notes field on the review request and we will answer it before anything else.

Do I have to switch carriers after a review?

No. A fair share of reviews end with us advising you to keep exactly what you have, sometimes with one endorsement added. You are told when staying put is the right answer.

Can I move a policy in the middle of its term?

Usually yes, and most carriers refund the unused premium on a pro-rata basis. It is worth checking for a short-rate cancellation penalty first, which we do before recommending any mid-term move.

What documents do you need to start?

The declarations page from each current policy, the year the property was built, roughly when the roof and main systems were last replaced, and the drivers and vehicles in the household. Nothing else at the start.

Why do two carriers quote such different prices for the same cover?

They weight the same facts differently — claims history, roof age, distance to a fire service, construction type and the mix of business they already hold in your area. A carrier that is expensive for one household can be the cheapest for the next street over.

Does bundling home and auto always cost less?

Often, not always. The bundle discount is real, but a carrier can be strong on auto and weak on home. We price both ways and show you the gap before you decide.

Will asking for quotes affect my credit?

Insurance quoting typically uses a soft inquiry that does not affect your credit score. We will tell you before anything is run, and you can decline the credit-based element — it may simply mean fewer carriers can quote.

What happens if I have a claim?

You report it to the carrier so the file opens immediately, then tell us. We read the relevant wording with you, explain how the deductible applies, and follow up when the adjuster goes quiet.

How quickly do you reply to a review request?

By email, within two working days, with either the review questions or a note telling you your current cover looks sound and no review is needed yet.

Request a policy review

Send what you have and we will read it

One short form. No obligation, no cold calls, and no pressure to move anything that is already working.

We reply by email within two working days.